
I will explain how RWA Tokenization transforms traditional assets like real estate, treasury bills, physical commodities, and private credit into blockchain-based digital tokens. By 2026, the finance ecosystem is expected more and more tokenization as a dominant force that provides opportunities for fractional ownership, ownership worldwide, and improved asset liquidity. It integrates the walls of the traditional finance system with the modes and platforms of the new digital economy. This will feature compliance, transparency, and economical efficiency. This tech will be at the center of the innovative ways to use the digital economy in the future.
What Is RWA Tokenization?
Real-world asset (RWA) tokenization involves the creation of a digital representation of either a physical or a financial asset on a blockchain. Like native digital assets (cryptocurrencies) that derive their value solely on a blockchain, RWA tokens derive their value from off-chain assets such as real estate, private credit, commodities, Treasury bills, or intellectual property.
RWA tokens are issued in a legal framework and are usually owned and managed by a special purpose vehicle (SPV) or a custody agent to ensure compliance and protection of investors’ interests. Tokenization allows for capital market innovation. Tokenization allows for the fractional ownership of an asset, accelerated settlement, automated administration, and global participation.
Tokenization serves to extend traditional finance into the decentralized finance ecosystem allowing legal ownership and control of assets. RWA tokenization of an asset facilitates capital raising in an efficient and inclusive manner and exemplifies the intersection of finance, law, and technology.
The Next Phase of Digital Finance in 2026
AI and Financial Systems
Financial-related systems will no longer be assistant-related AI, but will be used for the automation of decision-making systems and used for predictive analyses, fraud detection, and the offering of personalized financial services.
Tokenization and Real World Assets (RWA)
RWA tokenization provides opportunities for the fractional ownership of assets that are typically immobile such as bonds and a property, and helps create liquidity in typically less liquid investment markets.
The Regulation of Stablecoins
Regulations for stablecoins in the United States by the GENIUS Act of 2025 will help create a compliant and safe infrastructure for cross-border transactions.
Sovereign Digital Infrastructures
Countries like India are developing trustworthy systems (UPI and DigiLocker) that incorporate digital identity, payments, and credit.
Digital Finance
Global revenue in digital finance surpassed $650 billion by 2025, with innovations striking a balance between profitability and compliance.
International Payments
Blockchain technology is improving the time and cost of cross-border transactions for customers and businesses.
Comparison of 2026 Trends
| Trend | Impact | Example |
|---|---|---|
| AI in Finance | Autonomous systems, fraud prevention, predictive lending | AI-driven fintech challengers |
| RWA Tokenization | Liquidity, fractional ownership, global access | Real estate & treasury bill tokenization |
| Stablecoin Regulation | Compliance, trust, faster payments | GENIUS Act in US |
| Digital Infrastructure | Sovereign, scalable, interoperable | India’s UPI & DigiLocker |
| Fintech Growth | $650B revenue, IPO resurgence | Nubank, Adyen, Robinhood |
Why Do RWA Market-Size Estimates Vary?
The tokenization of real world assets/RWA tokenization is the process that uses blockchain technology in the representation of traditional assets or economic rights. This idea can be explained in relatively easy terms, however, measuring the scope of such a market is not that trivial.
The main reason is that different research firms and associations draw different market boundaries. Some firms consider only those assets that have been issued and are currently active on a blockchain. Other firms take a more comprehensive view and include, for example, stablecoins, the repo market, private credit, and assets that financial corporations plan to tokenize in the future.
Different approaches result in a significant disparity in the size of the markets estimated.
BCG, for example, in its 2026 report on asset management, states that the market for tokenized real world assets, excluding stablecoins and repos, is roughly $25 billion. However, BCG projects a more bullish view for this market over the next decade.
McKinsey has a more comprehensive estimate; it states that tokenized markets for financial assets could reach $2 trillion by 2030. However, McKinsey’s more optimistic view puts that figure at $4 trillion.
RWA Tokenization Market at a Glance
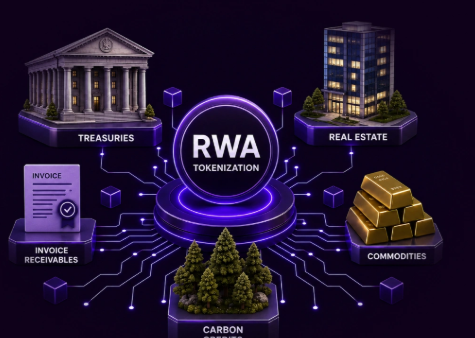
RWA tokenization uses blockchain technology to represent real-world assets as digital units. This can incorporate government and corporate bonds, securitized debt, money market, equities, commodities, and other financial instruments. When real estate and tokenized cash (e.g. stablecoins), Boston Consulting Group (BCG) projects that the potential market size could reach around $600 billion by 2026.
In BCG’s base-case scenario, they expect that the market could reach more than $14 trillion by 2030. The rapid growth of the market reflects the permissioned model of tokenization across multiple segments of the financial services industry as institutions begin to use blockchain technology to issue assets, trade, collateral, and service the assets.
| Metric | Snapshot |
|---|
| 2026 RWA tokenization market | ~$600 billion |
| 2030 BCG projection | ~$14 trillion |
| Market scope | Tokenized RWAs excluding real estate and tokenized money/stablecoins |
| Key asset classes | Government bonds, corporate bonds, securitized debt, money-market instruments, equities, commodities |
| Key institutional use cases | Funds, government securities, credit, collateral, settlement |
| Major example | BlackRock BUIDL |
| Institutional infrastructure milestone | DTCC’s move toward production-scale tokenization |
The $600 billion figure gives a rough estimate of the size of the tokenized RWA market in 2026, and the $14 trillion figure gives a rough estimate of the size of the market in the more distant future. BCG anticipates that government bonds, corporate bonds, securitized debt, money market instruments, equities and commodities will all play a role in this growth.
Tokenization goes well beyond the movement of existing assets to blockchains. There are many potential advantages of blockchain infrastructure to financial institutions, such as more efficient and timely settlement, easier collateral movement, programmable transactions, and optimized market interactions.
How Tokenization Works
Selection of Real-World Asset: A real estate, bond, or commodity asset is selected and legally verified.
Legal Framework: Compliance is achieved by taking ownership rights and placing these under an SPV or custodial arrangement.
Digital Token Representation: The asset is tokenized and digitized to represent fractional ownership on the blockchain.
Automated Rules: The issuance, transfer, and settlement of tokens is automated to reduce the need for manual work.
** Incremental Investments**: High-value assets are made accessible to investors through fractional ownership.
Trading and Liquidity: Illiquid assets are made liquid through trading on digital asset exchanges.
Security and Transparency: Transactions and ownership records are time-stamped and irrevocable on the blockchain.
What Is Driving Tokenization Growth in 2026?
Adoption of RWA tokenization is accelerating due to the introduction of clear compliance frameworks by governments, creating legal certainty and attracting institutional investment. Scalable and interoperable blockchains remove friction in the issuance and trading of asset backed tokens across networks.
Real world assets are evenly distributed across a greater number of investors, as fractional ownership is made possible by the growing interest in tokenized assets. Institutional investors prefer trades that are settled quickly and improve liquidity.
By comparison to traditional capital markets, tokenized assets can settle almost instantaneously. Tokenization of assets is further boosted by increasing AI driven finance integration, which provides risk management tools and optimal portfolio tools. In 2026, tokenization is the most dominant finance innovation.
Why Tokenization Matters in 2026
Unlocking Liquidity
Tokenization of an illiquid asset class like real estate or private credit makes those assets tradable and more liquid.
Fractional Ownership
Tokenization makes high value assets tradable. This means that investors, previously restricted by high minimum investment, can access and invest in high value assets.
Global Investment Opportunities
Blockchain technology removes the boundaries of traditional investment and makes tokenized assets tradeable across borders.
Transparency and Security
Tokenized ownership of assets on immutable blockchain ledgers is trustworthy and audit safe.
Legal Clarity
Legal frameworks which define tokenized assets are being created and word wide adaptation of tokenized assets by institutions is expected to follow.
Integration with AI
AI based analytics and risk management in an improved and optimized tokenized markets is expected.
Simplification
Manual and time intensive processes will be fully or partially automated by smart contracts.
Key Technologies Behind Tokenization
| Technology | Role in Tokenization | Example Platforms/Use Cases |
|---|---|---|
| Blockchain Settlement Layer | Provides immutable ledger, consensus, and transaction finality. | Ethereum, Polygon, Avalanche for RWA issuance. |
| Smart Contracts | Automates rules for issuance, transfer, compliance, and settlement. | ERC‑1400 security token standard, programmable dividends. |
| Compliance Layer | Handles KYC/AML, investor whitelisting, and regulatory enforcement. | On-chain identity verification, permissioned access. |
| Oracles & Data Feeds | Connects off-chain asset data (prices, maturity, legal events) to blockchain. | Chainlink oracles syncing treasury bill maturity dates. |
| Custody & Distribution | Ensures secure storage of underlying assets and token distribution. | Institutional custodians, SPVs, regulated trustees. |
| Tokenization Platforms | Middleware bridging TradFi and DeFi, managing lifecycle of tokenized assets. | Securitize, Polymesh, Fireblocks tokenization suite. |
| Interoperability Solutions | Enables cross-chain asset transfers and liquidity aggregation. | LayerZero, Cosmos IBC, cross-chain bridges. |
Benefits of Tokenized Assets
Liquidity Access: In tokenization, the liquidity bottleneck associated with the ownership of assets like real estate and private equity is removed.
Fractional Ownership: Tokenization enables smaller constituencies to own fractions of a high-value asset.
Global Reach: Blockchain technology means any asset can be traded irrespective of the country’s borders.
Transparency & Security: Blockchain technology is immutable, providing trust, auditability, and ownership control.
Efficiency Gains: Compliance and dividend distributions are effected by smart contracts, removing the inefficiency and costs associated with time.
Regulatory Confidence: The definition of tokenized assets by 2026 has removed the uncertainty for institutional adoption.
Portfolio Diversification: Newly accessible assets allow for the aligning of risk with yield engendering more optimal returns.
Tokenization and Traditional Finance
| Aspect | Tokenization | Traditional Finance |
|---|---|---|
| Ownership | Fractional, represented by blockchain tokens | Full or partial ownership via legal contracts |
| Liquidity | High, assets can be traded instantly on digital exchanges | Limited, often illiquid with lengthy settlement cycles |
| Accessibility | Global, borderless participation | Restricted by geography, intermediaries, and regulations |
| Transparency | Immutable blockchain records, real-time auditability | Opaque processes, dependent on intermediaries |
| Settlement | Automated via smart contracts, near-instant | Manual, multi-day settlement periods |
| Compliance | On-chain KYC/AML, programmable restrictions | Traditional regulatory filings and intermediaries |
| Cost Efficiency | Reduced fees through automation | Higher costs due to brokers, custodians, and paperwork |
| Innovation | AI-driven analytics, interoperability, programmable assets | Limited innovation, slower adoption of new tech |
Role of Stablecoins in Tokenized Finance
Liquidity Backbone
Tokenized Asset trading is immediately liquid thanks to settlement with stablecoins.
Price Stability
Reliability for asset trading is found in stablecoins since they are less volatile than cryptocurrencies.
Cross-border Payments
Stablecoins offer cheaper and quicker transfer of value across borders without the hassle of traditional banking.
On-chain Settlement
Payments and dividends can be automated and settled using stablecoins.
Regulatory Compliance
In 2026 with more regulations likely, stablecoins, if regulated, can provide trust to institutions.
Bridge Between TradFi & DeFi
Stablecoins, along with tokenized markets, unite traditional finance and decentralized finance.
Capital Efficiency
Stablecoins help build tokenized ecosystems by reducing reliance and associated costs of intermediaries.
Regulatory Landscape in 2026
Europe – MiCA Framework
In 2026 we can expect greater international regulation, including the frameworks set by the European Union’s (EU) Markets in Crypto-Assets (MiCA), which regulate asset-referenced tokens, e-money tokens and tokenized securities under the DLT Pilot Regime.
United States – SEC Digital Asset Frameworks
In 2026 we can also expect the further development of regulation in the United States (US) around the Securities and Exchange Commission’s (SEC) clarification of the digital asset framework, which sets the rules around when digitized assets become securities and therefore must be registered or recognized through an exemption. The SEC also set up a digital asset framework sandbox.
Asia-Pacific – Progressive Regulation
Singapore, Hong Kong, and Japan have established themselves as innovation hubs, having granted licenses for the operation of tokenized asset platforms.
India – Asset Tokenization Bill 2026
India published its first Bill for digital assets, which will include legal frameworks for asset tokens, a multi-regulatory structure and an investor protection framework. This will be used to curtail capital flight and provide protection for the estimated 12 crore investors currently using offshore platforms.
Challenges and Risks
Regulatory Fragmentation: Since different jurisdictions have different rules, a tokenizer’s ability to scale globally becomes limited.
Custody Issues: Safekeeping of the underlying real-world assets may be disputable and lead to legal battles.
Living up to Liquidity: The development of the secondary markets for tokenized assets may be slow, creating challenges for trading volume.
Living up to Cybersecurity: Smart contracts, especially oracles, may be vulnerable to attacks.
Unresolved Legal Concerns: Investors may not have a clear understanding of what they own as a token.
Market Manipulation Concerns: The highly fragmented markets, along with low liquidity, may create concerns for manipulating prices.
Complexity of Operations: Tokenization of assets in mainstream finance, when integrated, may call for considerable investments to set up the required infrastructure.
Tokenization vs Traditional Asset Infrastructure
| Aspect | Tokenization | Traditional Infrastructure |
|---|---|---|
| Ownership | Represented digitally via blockchain tokens, enabling fractional ownership | Legal contracts, certificates, and centralized registries |
| Settlement | Near-instant through smart contracts | Multi-day manual processes with intermediaries |
| Liquidity | High, assets can be traded globally on digital exchanges | Limited, illiquid markets with restricted access |
| Accessibility | Borderless participation, open to global investors | Restricted by geography, intermediaries, and regulations |
| Transparency | Immutable blockchain records, real-time auditability | Opaque systems, dependent on custodians and brokers |
| Compliance | Automated KYC/AML embedded in smart contracts | Manual filings, regulatory intermediaries |
| Cost Efficiency | Reduced fees via automation and disintermediation | Higher costs due to paperwork, custodians, and brokers |
| Innovation | AI-driven analytics, programmable assets, interoperability | Slow adoption of new technologies, legacy systems |
Real-World Use Cases
Tokenization has transformed many industries, including real estate and private credit, allowing retail investors access to once institutional exclusive real estate and private credit investments. Tokenized loans offer investors greater liquidity and accelerated settlement. Tokenized Treasury Bills and other similarly safe yield assets have been created.
Tokenization of physical commodities and Intellectual Property have created easier and more efficient markets for commodities and greater liquidity for creators. These uses of tokenization have created more efficient and liquid markets and show why tokenization will continue to dominate digital finance in 2026 and beyond.
Future of Tokenization
By bridging traditional finance with infrastructure that is decentralized, tokenization has the potential to faciliate the growth of a more liquid, transparent, and inclusive global market in the years to come.
Real estate, credit, and treasury bills will all have their assets fragmented and tokenized for borderless investment. The creation of liquid and legitimate markets will require additional regulations, such as MiCA in the EU and the proposed Asset Tokenization Bill in India. Enhancements in AI based analysis and blockchain interoperability will ease the management of risk and valuation, and will also create tradeable assets across different blockchains. Stablecoins and CBDCs will play the role of the settlement rails to enhance the speed of settlement while ensuring compliance.
Tokenization will quickly gain traction as a critical component of digital finance as the framework for the issuance, trading, and management of assets is transformed and fundamentally improved.
FAQs
What is tokenization?
Tokenization is the process of converting ownership rights in real-world assets into blockchain-based digital tokens.
Which assets can be tokenized?
Real estate, private credit, treasury bills, commodities, and even intellectual property can be tokenized.
Why does tokenization matter in 2026?
It unlocks liquidity, enables fractional ownership, and provides global accessibility with transparency and compliance.
What role do stablecoins play?
Stablecoins act as settlement rails, ensuring instant liquidity, cross-border payments, and regulatory trust.